Introduction
Most Philippine SMEs start their digital payments journey with a mix of apps: a bank app for transfers, an e-wallet account for daily sales, maybe a card reader borrowed for a weekend market, and a spreadsheet at closing time to make everything agree. This setup works fine when order volume is low. The moment sales pick up, the same manual matching becomes a bottleneck, eating hours that should go toward actually running the business. A digital business wallet for SMEs in the Philippines solves this by consolidating acceptance, reconciliation, and payout into a single account. It is not a stripped-down version of enterprise payment infrastructure built for small budgets. It is the same BSP-supervised, PCI DSS v4.0-certified backbone that large enterprises rely on, sized and priced for a growing small business.
Why Manual Reconciliation Quietly Drains Growing SMEs
Every unconnected payment channel adds its own login, its own settlement report, and its own format. An SME owner accepting an e-wallet, a card terminal, and bank transfers is effectively running three separate back offices by hand. Matching a customer’s proof of payment to an actual order takes minutes per transaction, and those minutes multiply with every sale. This is a hidden operational tax that scales directly with revenue, since the more a business grows, the heavier the manual load becomes rather than lighter.
Small and medium enterprises already make up a significant share of the country’s economic activity, and the ones that scale past this stage are usually the ones that replace manual matching with SME business solutions that offer a real-time transactions dashboard instead of a static end-of-day report. Owners who have lived through this shift describe the same recurring payment challenges: missed payments, delayed order fulfillment, and hours lost to spreadsheet matching every single day.
What BSP Supervision and PCI DSS v4.0 Actually Mean for a Small Business
Not every digital wallet operates under the same rules. A processing provider offering online payments for small businesses is directly supervised by the Bangko Sentral ng Pilipinas as a licensed Electronic Money Issuer and answers to a regulator that reviews how customer funds are held and moved. That is different from a wallet that simply rides on a bank’s infrastructure without carrying its own license. PCI DSS v4.0 certification adds a second layer of assurance.
It is the current global standard for how card data is stored, transmitted, and protected, and it requires ongoing, independently verified compliance rather than a one-time checklist. For a small business, these two credentials matter most when a customer asks a plain question: Is this safe? A school collecting tuition, an HOA collecting real estate dues, or an insurer collecting premiums through tokenization and click-to-pay all need a documented answer, not just a verbal assurance. Being able to point to BSP supervision and PCI DSS v4.0 certification gives an SME the same credibility a much larger enterprise would use in the same conversation.
One Wallet, 50+ Payment Channels: Ending the Multi-Provider Juggling Act
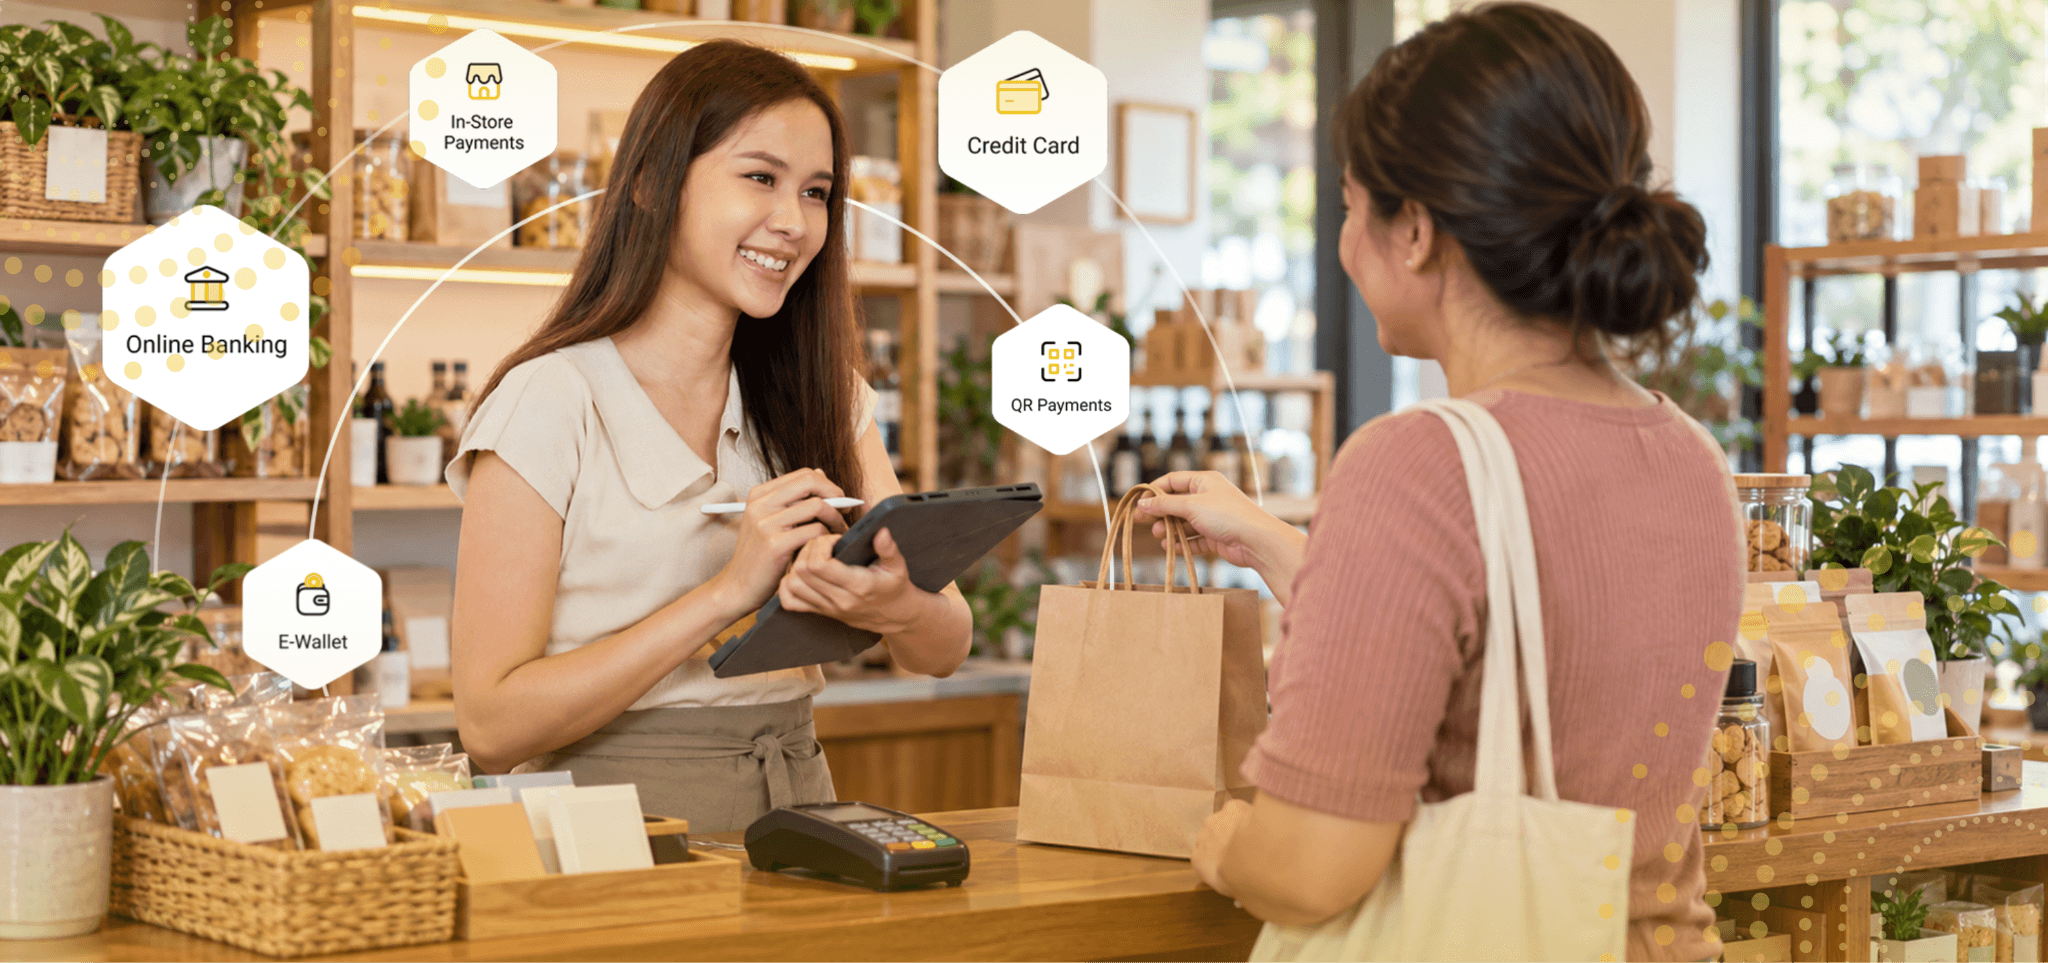
Filipino consumers now expect to pay however is most convenient to them at the moment of purchase: an e-wallet, a bank transfer, a card, or cash at a partner outlet. An SME that supports all of these preferences by signing up separately with each provider ends up multiplying its own back-office work, since every new channel means another login, another settlement schedule, and another report to reconcile by hand.
Consolidating acceptance under one wallet with more than 50 payment channels removes that multiplication. A single checkout page or payment link from a provider offering payment processing for small businesses can accept nearly any method a customer prefers, while the business still sees everything land in one place.
This matters even more for SME business solutions built for sectors without a website or an in-house developer: retailers with a physical stall, schools collecting fees, or travel operators collecting booking payments through a wallet rather than a full storefront. Channel breadth is not a marketing checkbox. It is what keeps a growing SME from having to choose between convenience for the customer and simplicity for the business.
How T+1 Payout Automation Frees Up SME Working Capital
Accepting a payment and actually having usable money are two different milestones, and the gap between them is where a lot of SME working capital gets stuck. A sale that settles into the business account after several days still needs to be paid for immediately, in supplier costs, payroll, and inventory. Automated T+1 payout processing shortens that gap to the next business day, which means collected revenue becomes usable capital far sooner than a manual or batch settlement cycle allows.
For a business managing tight cash flow, this single change often has more day-to-day impact than any promotion could. Faster payouts also reduce the pressure to hold extra buffer capital just to cover the lag between a sale and its settlement, freeing that money to go toward growth instead of sitting idle while a payment clears.
5 Signs Your SME Has Outgrown Manual Payment Collection
1. Spending More Time Matching Payment Notifications to Orders
If closing the books now takes noticeably longer than it did six months ago, transaction volume has already outpaced the manual process behind it.
2. Lack of Payment Options Customers Prefer
A customer asking for a payment method the business does not support is a sale walking away, not just a minor inconvenience.
3. Being Asked for Compliance Credentials
Government offices, schools, and corporate clients increasingly ask vendors to prove regulatory and security compliance before onboarding them at all.
4. Delayed Payments Due to Unsettled Collected Funds
Money already collected but not yet settled cannot cover this week’s supplier invoice or payroll run.
5. Reconciling More Than Two Payment Channels by Hand
Every additional channel added without a shared dashboard multiplies the daily matching work instead of simply adding to it.
Why a Digital Business Wallet by Paynamics Works for Your Business
Paynamics brings BSP-supervised, PCI DSS v4.0-certified acceptance, real-time reconciliation, and T+1 payout automation into one business wallet built for Philippine SMEs. Merchants get more than 50 payment channels without juggling separate providers, and every transaction lands on a live dashboard instead of a stack of end-of-day reports. For a digital business wallet for SMEs in the Philippines, this means enterprise-grade infrastructure without enterprise-grade complexity, already trusted by schools, real estate developers, insurers, and retailers across the country.
Conclusion
Manual reconciliation and slow payouts are quiet costs that most SMEs only notice once they have already outgrown their current setup. A digital business wallet for SMEs in the Philippines replaces both problems at once: one account for every payment channel, one dashboard that reconciles in real time, and payouts that land the next business day instead of several days later.
Government offices, schools, real estate developers, and insurance clients increasingly expect the level of trust that only a regulated, verifiable provider can offer. Explore what Paynamics’ Business Wallet can do for your operations and see how quickly manual matching can become a thing of the past.