Introduction
A card, wallet, bank transfer, and QR code biller operating at scale cannot operate on instinct. It needs a partner it can trust and be accountable to a regulator. With Paynamics’ transaction monitoring solutions, you get a provider that runs on a platform operated by an Electronic Money Issuer supervised by the Bangko Sentral ng Pilipinas, with many years of experience in both the enterprise and government space.
This article breaks down a practical checklist that a finance and procurement team can use to compare options, along with an explanation of how transaction monitoring that feeds into T+1 payouts effectively removes most manual reconciliation. Philippine businesses are living this pain today. Consumers are paying digitally in ever-increasing numbers, and the back office is still doing all the manual matching. Every additional channel is another file to reconcile.
What Transaction Monitoring Means for Billers and Why Regulation Shapes It
Transaction monitoring is the ongoing review of payment activity to detect any unusual activity, to confirm what’s been collected, and to maintain an auditable trail. In the Philippines, the rules are based on the Anti-Money Laundering Act and the Anti-Money Laundering Council. BSP Circular 706 sets out the program requirements for supervised institutions: customer due diligence, monitoring, record keeping, and reporting. Electronic money issuers are among the covered persons.
Records must be kept for a minimum of 5 years, and suspicious transactions must be reported to the AMLC within 5 working days of identification. The biller doesn’t do the reporting; it’s the payment partner that does. You’ll want to pick a provider like Paynamics for its transaction monitoring solutions, as it already meets the standard, prevents gaps in your own surveillance, and helps you answer audit questions at the end of the day. The BSP has been keeping the pressure on, so you’ll ultimately be exposed if you have a partner with poor monitoring.
Transaction Monitoring Software Vendors: A Buyer’s Checklist for Enterprise Billers
Most buyers’ guides for transaction monitoring software vendors converge on the same key criteria. Volume and speed are the top considerations. The system must decide before the payment clears, and Stripe makes it clear that any additional latency at that point will cost you at checkout. Rule flexibility is also important, since you should be able to change rules as you go without having to go back to the vendor. Integration effort, reporting capability, security certification, regulatory standing, support, and total cost are all things you’ll have to factor in. The exercise should start with your own monitoring requirements rather than the vendor’s feature list.
A transaction monitoring solutions partner would be up to the task, with government bodies and large enterprises already in the client and merchant base. They can support multiple payment channels and run the entire acceptance, payouts, and wallets proposition in one ecosystem, so you don’t have to piece transaction data together from multiple disparate providers. PCI DSS v4.0 and BSP supervision are absolute must-haves.
From Manual Spreadsheets to Real-Time Reports on the PTI Dashboard
Manual reconciliation is a well-worn process. You get the exports from each channel, you match them to the bank credits, you chase the exceptions, and you’re still left with a very late month-end. Automated matching software compares records against bank statements, the ERP, and payment gateways, then continuously matches them to enable a much faster close. In 2025, digital payments were 64.69% of retail volume, just 18.75% of business payments were digital, and finance teams are still doing manual reconciliation.
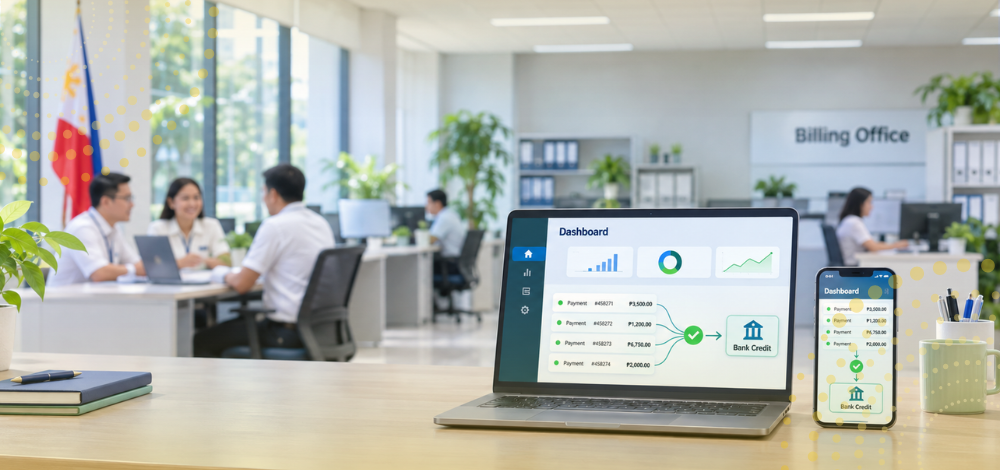
On the payment dashboard, you have the transaction reports in real time so Finance can see collections as they happen. Anomalies are flagged on the same day, and collections are confirmed without having to wait for a bank statement. A checkout brings all the card, wallet, online banking, and installment activity together so you end up with one screen rather than a folder of exports.
Good transaction monitoring also maintains a history, which is crucial when an auditor asks why a payment was held or released. You need to provide that history for that type of review, and the same view can be used for fraud checks, since any odd spike will be immediately obvious.
Monitoring Tied to T+1 Payout Automation: What You See Is What Lands
Monitoring only helps the finance side if it’s linked to the money. With T+1 payout automation, the transactions on the dashboard match the funds credited, so there’s no need for a separate matching exercise. T+1 is settled one business day after the transaction day.
Ask every vendor how they treat weekends, holidays, and cut-off times, as that’s what’s going to determine when the Friday collections actually hit your account. Get the current schedule from your finance team and build that into your treasury calendar. A school that bills on the 1st of the month or a utility with a very significant collection day will be affected by the cut-off more than a retailer with fairly steady daily sales. Knowing the rule in advance makes the surprise a line on the calendar.
7 Questions to Ask Any Transaction Monitoring Vendor Before You Sign
Use this list of questions to compare Paynamics’ transaction monitoring solutions against any vendor on your shortlist. Each question comes with a quick answer to listen for.
1. Is the vendor BSP-supervised?
Yes, with a license you can verify directly with the regulator, such as an Electronic Money Issuer (EMI) registration.
2. Is it PCI DSS v4.0 certified?
Yes, with a current certification that covers the services you will actually use.
3. Are reports real-time?
Yes. Transactions show up as they happen, not in next-day files.
4. Do dashboard totals reconcile to payouts?
Yes. Totals match bank credits with no manual adjustments, so finance doesn’t need a side spreadsheet.
5. What is the payout cycle?
T+1, with published cutoff times and clear holiday rules.
6. Can it handle enterprise and government volumes?
Yes, backed by references from large billers and public agencies, plus proof of stable performance on peak billing days.
7. Does it cover acceptance, payouts, and wallets in one ecosystem?
Yes. One platform, one dashboard, and no stack of separate contracts.
See It, Match It, Get Paid: Paynamics Dashboard and T+1 Payout Solutions
With Paynamics’ Checkout, it feeds the PTI dashboard with real-time transaction reports across 50+ channels. Payout Solutions will auto-settle T+1 and match on-screen what actually arrives. Billers with no dev and no website can get going with Payment Pages, which requires no API integration at all.
The Paynamics Business Wallet comes with trackable QR codes and payment links for each branch. Ideal for retailers using QR Ph, schools taking fees, and travel operators taking booking fees. Insurers can use tokenization in conjunction with click-to-pay, and real estate billers can collect their HOA dues and monthly payments all on the same dashboard. Billers can now get transaction monitoring services with visibility, matching, and payout all in one place.
Conclusion
A good vendor will answer all seven questions without any hesitation. Paynamics does and has the BSP supervised license, PCI DSS v4.0 certification, 5000+ merchants, and 50+ payment channels to back it up. The dashboard provides real-time visibility into each collection, and the same data drives the T+1 payouts reported to your account. That’s the promise of Paynamics’ transaction monitoring solutions for enterprise and government billers.
Review Paynamics’ solutions and speak with the team about your collection flows.